
Subscription payments are recurring charges your platform bills automatically on an agreed schedule, and running them correctly means capturing clear consent from the customer and keeping auditable authorization records for every charge. Before you pick software, decide whether a hosted checkout or a tokenized API fits your engineering resources. That single choice shapes your compliance exposure, your PCI scope, and how fast you can launch.
TL;DR:
- Using a clear authorization record and separate charge execution is essential to meet compliance; billing cadence and proration must be established before launch.
- Card payments remain prevalent but carry high chargeback risks, while ACH and direct debit are cheaper but require longer confirmation times; wallets improve checkout speed and BNPL broadens buyer pools at added complexity.
- Setting up subscription payments involves choosing pricing, crafting disclosures, selecting integration methods, and testing full cycles before opening to customers.
- Maintaining a self-service dashboard, prompt payment updates, and structured dunning reduces failed payments and customer frustration over cancellations.
- Compliance with negative-option rules mandates transparent disclosures, express consent, and easy cancellation processes, with recordkeeping of authorization data to shorten dispute resolution.
Table of Contents
- How subscription and recurring payments actually work
- Payment methods that support recurring billing and their trade-offs
- Setting up your business to accept subscription payments
- Managing subscriptions day to day without losing customers
- Compliance essentials for negative-option and auto-renew subscriptions
- Security and PCI compliance for recurring billing
- Choosing a subscription billing solution as an SMB
- Implementation checklist and pro tips for launch week
- Handling international subscriptions and currency considerations
- Costs and timelines you should plan for
- Common challenges in subscription payments and how to fix them
- Communicating with subscribers to reduce disputes and churn
- Connecting your billing setup to the rest of your sales stack
- Publisher perspective: where subscription billing usually goes wrong
- Commas as an integrated option for subscription billing and funnels
- Sources
- FAQ
How subscription and recurring payments actually work
A subscription charge is not one event. It starts with an authorization, the customer's explicit agreement to be billed on a schedule, and that authorization has to be something you can produce later if a bank or regulator asks for it. The charge itself is a separate action your system triggers on each billing date using the stored payment token.

Billing cadence determines a lot of downstream logic: monthly, annual, or usage-based cycles each need their own proration rules when a customer upgrades or downgrades mid-cycle. Trial-to-paid conversion is its own decision point, since converting a free trial into a paid subscription counts as a new charge that needs its own disclosure at signup, not just a mention buried in trial terms.
Negative-option billing, where the subscription renews unless the customer actively cancels, carries the heaviest compliance weight because regulators require material terms to be disclosed every time a consumer agrees to recurring charges.
- Authorization is the consent record; the charge is the execution, and you need both stored separately.
- Billing cadence and proration rules must be defined before checkout goes live, not patched in after complaints arrive.
- Trial-to-paid conversion requires its own disclosure, since it triggers a new charge under a negative-option pattern.
Payment methods that support recurring billing and their trade-offs
Card payments remain the default for most subscription businesses because tokenization lets you store a secure reference instead of raw card numbers, which keeps settlement fast and predictable. The trade-off is chargeback exposure: cardholders can dispute a subscription charge months after it posts, and disputes tied to unclear cancellation terms are increasingly common enforcement targets.
ACH and direct debit cost less per transaction and suit higher-ticket recurring offers, but they require a signed mandate or authorization form and carry longer return windows, sometimes weeks, before a failed debit is confirmed. That delay matters if you are relying on ACH for a high-dollar monthly coaching program and need to know quickly whether a payment actually cleared.
Digital wallets and pay-by-bank options speed up checkout and reduce cart abandonment, since customers authenticate with a device instead of typing card numbers, and settlement often happens faster than a traditional card cycle. Federal Reserve research on payment method adoption shows how consumer behavior varies across these newer rails, which is worth factoring into checkout design.
Buy now, pay later options can widen your buyer pool for a high-ticket offer, but they add complexity: BNPL providers typically want their own integration, and refunds or partial cancellations on a BNPL-financed subscription often follow a different timeline than a standard card refund.
- Cards offer speed and reach but carry the highest chargeback exposure of the common methods.
- ACH and direct debit cost less but need signed mandates and longer confirmation windows.
- Wallets and pay-by-bank improve checkout speed with fewer manual entry errors.
- BNPL can expand your buyer pool but adds a separate integration and refund timeline to manage.
Setting up your business to accept subscription payments
Getting from zero to a working subscription checkout takes a defined sequence, not trial and error.
- Choose your pricing model and billing cadence. Decide between fixed, tiered, or usage-based pricing, and lock in whether billing runs monthly, annually, or on a custom cycle before building anything else.
- Write the checkout disclosure and consent language. Material terms, price, frequency, and cancellation method need to appear at the point of consent, not in a linked terms page.
- Pick your integration method. A hosted checkout page reduces your technical lift and PCI exposure; an embedded tokenized field gives more design control; direct capture puts the most compliance burden on you.
- Run test transactions. Process a full cycle, including a trial conversion and a failed payment, before taking real customer money.
- Configure trial rules, proration, invoicing, and notifications. Set how trials convert, how upgrades are prorated, and when receipts and renewal notices go out.
Pro Tip: Build your cancellation flow before your signup flow goes live. Regulators expect cancellation to be at least as easy as signing up, and retrofitting it later means rebuilding customer trust along with the code.
Managing subscriptions day to day without losing customers
Once subscriptions are live, the operational work shifts to keeping them healthy. Customers expect a self-service dashboard where they can see their next billing date, update a card, or cancel without contacting support for every request. Internally, your team needs the same visibility to answer billing questions without digging through raw transaction logs.
Payment method updates deserve their own workflow: when a card expires or a token becomes invalid, the system should prompt a reauthorization rather than silently failing the next charge. Dunning, the process of retrying failed payments and messaging the customer, works best with a defined schedule (a retry at day one, another at day three, a final notice before pausing the account) rather than an indefinite retry loop that annoys the customer or triggers repeat decline fees.
Cancellation flows need to match the ease of the original signup. A customer who subscribed in two clicks should be able to cancel in a similarly small number of steps, and every cancellation should log a timestamp and confirmation record you can produce if a dispute comes in later.
- A self-service dashboard should show billing date, payment method, and cancellation option in one place.
- Payment method updates should trigger reauthorization prompts, not silent failures.
- Dunning schedules need defined retry windows and a clear point where the account pauses.
- Cancellation logs should capture the timestamp and method used, matching the ease of signup.
Compliance essentials for negative-option and auto-renew subscriptions
The FTC's amended Negative Option Rule requires sellers to disclose material terms before collecting billing information, obtain express informed consent for the recurring charge itself, and provide a cancellation method that is at least as easy as signing up. Burying these terms in a general terms-of-service page does not satisfy the disclosure requirement.
The CFPB has separately warned companies that they need clear consumer authorization for recurring auto-debits and records of that authorization's terms, since poor documentation raises both consumer harm and enforcement risk. FTC enforcement guidance on negative-option marketing reinforces the same three pillars: disclosure, consent, and cancellation.
Storing the right authorization data shortens dispute resolution. CFPB guidance recommends keeping the exact consent text shown at signup along with a timestamp, account ID, and payment token, since these four items materially shorten the time it takes to resolve a dispute.
Practical disclosure checklist:
- Show price, frequency, and cancellation method at the point of consent, not after checkout.
- Send a pre-charge notice if your terms or a card network require one.
- Provide a cancellation path that matches the number of steps it took to sign up.
- Store consent text, timestamp, account ID, and payment token for every authorization.
Security and PCI compliance for recurring billing
How you integrate payments determines how much PCI scope your business carries. PCI DSS guidance on self-assessment questionnaires shows that hosted payment pages and tokenized flows can significantly reduce a merchant's scope compared with capturing card data directly on your own servers.
Smaller merchants handling recurring virtual terminal transactions may fall under SAQ C-VT, while those embedding a tokenized field into their own checkout page may qualify for SAQ A-EP, both narrower than the scope required for direct capture. Choosing a hosted page from a PCI-validated provider often lowers audit burden and reduces the risk of accidentally capturing raw card data in logs or support tickets.
Regardless of which SAQ applies, a few controls belong in every setup:
- Tokenize card data at the point of entry instead of storing raw numbers anywhere in your systems.
- Limit how long you retain any payment-related data to what your dispute and audit needs require.
- Keep secure, access-controlled logs of authorization events separate from general application logs.
Choosing a subscription billing solution as an SMB
Evaluate any subscription billing option against your actual operational needs, not a feature checklist someone else wrote.
- Integration cost: a hosted checkout needs the least engineering time; a direct API integration needs the most.
- Feature fit: confirm trial handling, proration, usage metering, and dunning automation work the way your pricing model needs.
- Compliance support: look for built-in consent logging and exportable authorization records.
- Migration path: check how existing subscribers and payment tokens transfer if you switch platforms later.
Implementation checklist and pro tips for launch week
Before launch, verify every trial conversion, proration, and failed-payment scenario runs correctly in a test environment, including edge cases like gift subscriptions that should not auto-renew and mid-cycle upgrades.
- Confirm consent language displays at checkout and matches your stored authorization text.
- Run a full test cycle: signup, trial conversion, one failed payment, and one cancellation.
- Set your 30/60/90-day monitoring points for failed-payment rate, dispute rate, and post-trial churn.
Pro Tip: Test your cancellation flow the same week you test your signup flow. If cancellation takes more clicks than signup, fix it before launch, not after your first complaint.
Handling international subscriptions and currency considerations
Selling subscriptions across borders adds two layers most domestic-only setups do not need to think about: currency and tax. Charging in a customer's local currency generally improves conversion, but it means your billing system needs to handle exchange rate fluctuations between billing cycles without silently changing the amount a customer expects.
Tax obligations vary by country and, within some regions, by the buyer's location rather than the seller's. Digital subscriptions often fall under different tax rules than physical goods, and a subscription business selling into multiple countries needs to confirm registration and collection requirements for each market it serves rather than assuming one home-country rule applies everywhere. This is a case where the specific obligation depends entirely on where your customer is located and what you are selling, so treat it as a legal and tax question for a qualified professional in each relevant market rather than a one-size answer.
Cross-border subscriptions also complicate dispute handling, since a chargeback filed through an international card network can take longer to resolve than a domestic one, and currency conversion fees can eat into a subscription's margin if not priced in from the start.
Costs and timelines you should plan for
Setting up subscription billing rarely happens overnight, even with a hosted checkout. Expect design and disclosure work, testing, and integration time before your first live charge, with the exact timeline depending on how many payment methods and pricing tiers you support at launch.
Transaction fees vary by payment method and provider, and they are not the only cost: chargeback fees, failed-payment retry costs, and the staff time spent on dunning and customer support all add up over a subscription's lifetime. Refund windows also differ by payment method. Card refunds typically process faster than ACH reversals, and BNPL-financed subscriptions often follow the provider's own refund timeline rather than your standard policy.
Chargeback and retry timelines matter for cash flow planning. A disputed card charge can take weeks to resolve, and during that window the disputed amount is often held or reversed rather than available to you. Building a buffer into your revenue forecasting for pending disputes and retry cycles avoids surprises when a chargeback lands during a slow month.
Common challenges in subscription payments and how to fix them
Failed payments are the most frequent operational headache in subscription billing, usually caused by expired cards, insufficient funds, or bank fraud filters flagging a recurring charge. A defined dunning schedule with automatic retries and clear customer messaging recovers a meaningful share of these failures without manual intervention.
Customer churn tied to payment friction is a separate but related problem. A customer who wants to stay subscribed but whose card fails at renewal is a different case than a customer who wants to cancel, and treating both the same way (an aggressive retry loop with no communication) tends to push the first group toward canceling out of frustration.
Payment method updates cause a quieter but persistent problem: a customer who gets a new card number rarely thinks to update every subscription manually. Some card networks support automatic account updater services that refresh tokens behind the scenes, reducing failed payments caused simply by card reissuance rather than genuine non-payment.
Communicating with subscribers to reduce disputes and churn
Clear, timely communication does more to protect a subscription business than almost any billing feature. Renewal notices sent a few days before a charge give customers a chance to update a card or cancel before the charge posts, which reduces both failed payments and surprise disputes.
Failed payment alerts should go out immediately, with a direct link to update the payment method rather than a generic "your payment failed" message. Trial period communication matters just as much: a customer approaching the end of a free trial should get a clear notice of the exact date and amount of the first paid charge, since regulators specifically require this disclosure for negative-option conversions.
Cancellation confirmation emails close the loop and double as part of your audit-ready recordkeeping, giving the customer written proof the cancellation went through and giving you a timestamped record if a dispute arises later.
Connecting your billing setup to the rest of your sales stack
Subscription billing rarely operates alone. Most businesses need it to connect with a checkout or funnel builder, an email or SMS notification system, and often an affiliate program if partners help sell the offer. Readers distributing subscription offers through affiliates should pay particular attention to accurate disclosure and tracking, since affiliate-driven signups still carry the same consent and disclosure obligations as direct ones. For guidance on building and disclosing affiliate-driven traffic accurately, see BabyLoveGrowth's resource on affiliate program setup.

Integration options generally fall into three categories: a fully hosted checkout that handles billing and disclosure together, an embedded API that gives more design control at the cost of more engineering work, and a standalone billing tool that connects to your existing checkout through webhooks. The right choice depends on how much engineering time you have and how tightly you need billing tied to your funnel and community tools, something worth mapping out on our payments page if you are weighing a combined checkout and billing setup.
Publisher perspective: where subscription billing usually goes wrong
The businesses that struggle with subscription billing almost never have a technology problem first. They have a documentation problem: no stored proof of consent, no logged cancellation confirmations, and cancellation flows built to be harder than signup on purpose. That approach might reduce cancellations short term, but it is the exact pattern regulators are actively targeting, and it erodes the trust that keeps subscribers paying month after month.
— FanBasis
Commas as an integrated option for subscription billing and funnels
If you are selling a $1,000 to $10,000 offer, the operational overhead of stitching together separate checkout, funnel, and billing tools adds up fast. Some platforms combine checkout, funnel building, and subscription management in one account, and use regulated payment partners, which can cut down the integration work described throughout this guide.
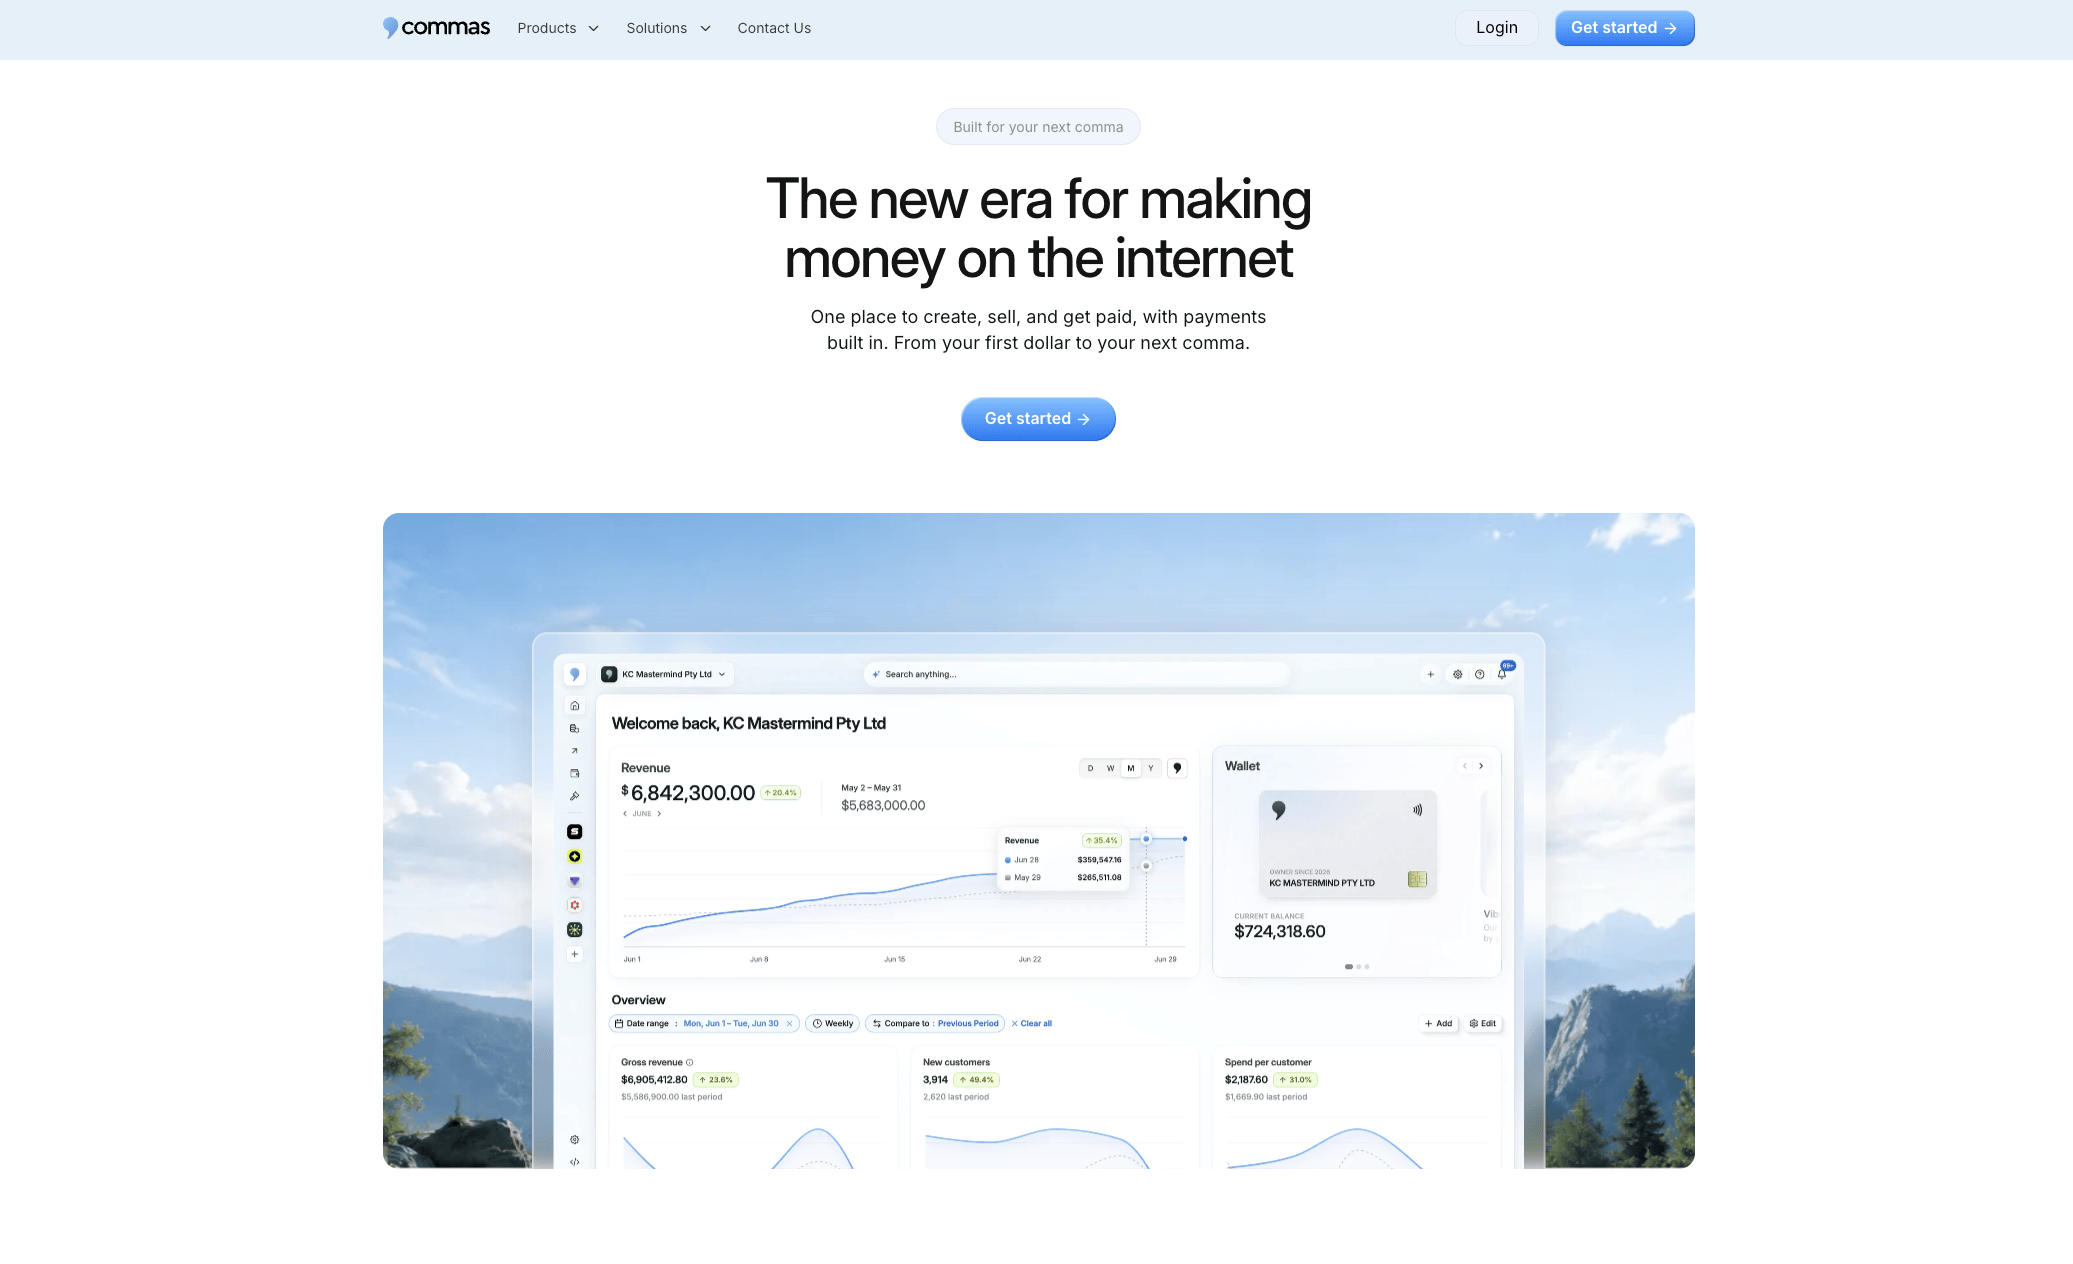
- Built-in dunning and retry logic reduce the manual work of chasing failed payments.
- Funnel and checkout live in the same account, so consent and disclosure language stays consistent across the buying flow.
- Course, community, and webinar sellers can manage recurring billing without a separate subscription tool.
If your current setup involves juggling a checkout page, a billing tool, and a funnel builder that do not talk to each other, evaluate Commas Payments or Vibe Funnels to see whether a single account covers what you need.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- Click to Cancel: The FTC’s amended Negative Option Rule and what it means for your business | Federal Trade Commission
- CFPB Alerts Companies About Obtaining Consumer Authorization For Recurring Auto Debits | Consumer Financial Protection Bureau
- Enforcement Policy Statement Regarding Negative Option Marketing | Federal Trade Commission
- PCI DSS v4.0 SAQ C-VT (excerpt) | PCI Security Standards Council
FAQ
How do I find all the subscriptions I'm paying for?
Check recurring charges on recent bank and card statements, since most subscriptions post under a recognizable merchant name each billing cycle. Some banking apps also flag recurring charges automatically, which is a faster way to spot ones you forgot about.
What is the best way to pay for subscriptions?
The best method depends on the amount and frequency: cards work well for most recurring charges because of tokenization and buyer protections, while ACH or direct debit often costs less for larger, less frequent charges. Choose based on how quickly you need payment confirmation and how comfortable you are with each method's dispute process.
How do I see my active subscriptions?
Most subscription providers offer a self-service dashboard showing your next billing date, payment method, and cancellation option in one place. If a business does not offer this, your bank or card statement remains the most reliable way to track what is actively charging you.
What is the best website for a subscription service?
The right platform depends on what you are selling and how you are selling it. Course creators, coaches, and community owners often want billing bundled with checkout and funnel tools, while businesses with existing infrastructure may prefer a standalone billing API instead.
How do subscription payments actually get authorized?
A subscription payment starts with the customer giving express consent to be billed on a recurring schedule, which the seller must disclose clearly at the point of signup. FTC rules require that this consent be informed and separate from general terms of service, and the seller should keep a record of the exact terms the customer agreed to.