
The fastest, lowest-friction way to accept international payments online is a payments platform that supports multicurrency settlement, local payment methods, and built-in fraud and compliance tooling. From there, show local-currency prices in each market, keep FX markups visible, and test your checkout regularly against authorization rates. Everything else, gateways, wallets, bank rails, is a variation on that formula.
TL;DR:
- Cross-border merchants should prioritize platforms offering multicurrency support, local payment methods, and fraud tooling to optimize international sales.
- Payment method choices depend on regional familiarity, with cards being costly for cross-border use and local wallets often yielding higher conversions where they are supported.
- Understanding true transaction costs involves tracking all fees, including interchange, FX markups, and payout charges, rather than relying on advertised rates alone.
- Compliance and KYC requirements, such as updating beneficial ownership and responding promptly to requests, are crucial to maintaining merchant accounts and avoiding de-risking.
- Localized checkout presentation, including showing prices in local currency and highlighting preferred payment methods, significantly reduces abandonment rates among international buyers.
Table of Contents
- Ways to Accept Payments Worldwide
- How Do You Choose a Payment Platform for Cross-Border Sales?
- Multicurrency Settlement: Cutting FX Costs Without Losing Sales
- What Does a Cross-Border Transaction Really Cost?
- Staying Compliant Without Losing Your Merchant Account
- Checkout Design That Converts International Buyers
- Why Integration Matters More Than Any Single Feature
- What Tax and Regulatory Rules Apply to Foreign Payments?
- Cutting Chargebacks on International Orders
- Managing Refunds Across Borders
- Supporting International Buyers Across Time Zones and Languages
- Data Privacy and PCI DSS for Cross-Border Transactions
- A Founder's Take on What Actually Trips Merchants Up
- Sell Globally Without Juggling Five Different Tools
- Sources
- FAQ
Ways to Accept Payments Worldwide
Most cross-border sales run through four channels, and each one fits a different customer and price point. Cards remain the default for one-time purchases above $50, especially in North America and Western Europe, but interchange and cross-border fees stack up fast. Local digital wallets (Alipay in China, GrabPay in Southeast Asia, UPI-linked apps in India) often convert better than cards in their home markets because customers trust them more than typing in a 16-digit number to a foreign merchant. Bank transfers, including SWIFT, still dominate for large B2B invoices where speed matters less than certainty, though settlement can take two to five business days. Local instant-payment rails and buy-now-pay-later options are gaining ground fast for mid-ticket digital products, particularly with younger buyers who dislike carrying a balance on a card.
- Cards: familiar everywhere, but costliest for cross-border acceptance due to interchange and currency-conversion fees.
- Local wallets: higher trust and conversion in specific markets, but require per-country integration.
- Bank transfers/SWIFT: reliable for large invoices, slow for anything urgent.
- Instant rails and BNPL: growing fast for digital goods, variable by region and regulatory maturity.
None of these is universally "best." The right mix depends on where your buyers live and how much they're spending, which is exactly why research into target markets has to come before any integration decision.
How Do You Choose a Payment Platform for Cross-Border Sales?
Picking a provider starts with matching its coverage to your actual customer map, not the other way around. A platform that handles cards beautifully but has no local wallet support in Southeast Asia is the wrong choice if that's where half your traffic originates.
Run through this checklist before signing anything:
- Multicurrency support. Can the platform price in the customer's local currency and settle payouts in yours, or does it force conversion at checkout?
- Local method coverage. Does it support the wallets, instant rails, and BNPL options your target markets actually use, not just cards?
- Payout currencies and cadence. How often does money land in your account, and in which currencies can you receive it?
- Security posture. Is it PCI DSS compliant, and does it support 3D Secure and Strong Customer Authentication where required?
- Developer tools. Are there SDKs, webhooks, and documentation good enough that your team isn't stuck guessing at edge cases?
- Chargeback and dispute support. Does the provider give you evidence templates and response windows, or leave you to figure it out?
Integration approach matters almost as much as the provider itself. A hosted checkout gets you live in days and offloads PCI scope, but you lose some control over branding and flow. An embedded API integration gives you full control over checkout UX and lets you optimize conversion aggressively, at the cost of engineering time. Payment links sit in between, useful for invoicing, one-off sales, or creators who don't want a full storefront build.
Pro Tip: Ask any shortlisted provider for their average settlement time and documentation requirements in writing before you sign. Verbal promises about "fast payouts" tend to evaporate the moment your account looks unusual to their risk team.
Multicurrency Settlement: Cutting FX Costs Without Losing Sales
You have three basic choices once money starts arriving in currencies you didn't ask for: auto-convert everything to your home currency immediately, hold multiple currency balances and convert on your own schedule, or work with a provider offering localized acquiring in your top markets. Each one shifts risk and cost differently.
Auto-conversion is simplest operationally but usually carries the widest spread, since the provider controls both the rate and the timing. Holding balances in the currencies you're paid in gives you control over when to convert, useful if you can absorb short-term volatility while waiting for a better rate. Localized acquiring, where transactions settle as if you had a local entity, tends to improve authorization rates and can reduce the cross-border fees banks tack onto foreign-issued cards.
The World Bank reported a global average cost of 6.5% to send $200 across borders in the first quarter of 2025, a number that puts real weight behind shopping FX spreads instead of accepting whatever your default processor quotes.
- Test auto-conversion against a currency-holding setup on a sample of 50 to 100 transactions before committing.
- Ask providers for their realized conversion spread on settled transactions, not just their advertised rate.
- Revisit your settlement currency choice every two to three quarters as your revenue mix shifts.
What Does a Cross-Border Transaction Really Cost?
Every international sale carries more fee layers than a domestic one, and most merchants only see the ones itemized on their statement. The full stack usually includes: the gateway fee, the acquirer's margin, interchange (set by card networks and often higher for cross-border cards), the FX markup on conversion, a payout fee to move money to your bank, and potential chargeback fees if a dispute lands.
To calculate your real cost per transaction, add every fee percentage and flat charge that applies to a given sale, then divide by the transaction amount.
- List every fee line on your last three statements, not just the headline rate.
- Ask whether cross-border and FX fees are itemized separately or bundled into a single opaque line.
- Negotiate volume-based discounts once you're processing consistently. Most providers have room below their published rates.
Comparing total cost per transaction rather than headline percentages is the only way to know if a "low-fee" provider is actually cheaper once conversion spreads are counted.
Staying Compliant Without Losing Your Merchant Account
Banks and payment processors apply a risk-based lens to every cross-border merchant, and the documentation they ask for reflects that. Expect to provide beneficial-ownership information, a clear description of your business model, and standard KYC documents before you can process meaningful volume internationally. FATF's guidance on correspondent banking makes clear that weak compliance postures are a leading cause of de-risking, where banks simply close accounts rather than manage the perceived risk.
The way to avoid that is proactive, not reactive: keep your business description current with your processor, respond quickly to information requests, and flag major changes (new markets, new product lines, sudden volume spikes) before they trigger an automated review.
- Maintain clean, current beneficial-ownership records and update them whenever ownership changes.
- Respond to KYC requests within days, not weeks. Slow responses read as evasion to automated risk systems.
- Document your business model clearly enough that a reviewer unfamiliar with your niche can understand it in one read.
On fraud, Strong Customer Authentication measurably lowers fraud rates, and cross-border card transactions outside the EEA show meaningfully higher fraud rates than domestic ones. Layer 3D Secure, velocity checks, and method-level orchestration (routing riskier transactions through additional verification) rather than relying on a single fraud filter.
Pro Tip: Keep a simple compliance folder updated quarterly: business description, ownership chart, and a one-page summary of your payment volume by market. When a processor asks, you send it in minutes instead of scrambling for a week while your payouts sit frozen.
Checkout Design That Converts International Buyers
Buyers abandon checkouts fastest when the price looks wrong or the payment method feels unfamiliar. Fix both.
- Show prices in the local currency, not just your home currency with a "converted at checkout" disclaimer.
- Surface the two or three payment methods most used in that buyer's country first, rather than defaulting to a card field.
- A/B test hosted checkout against an embedded flow. The difference in completion rate is often larger than most merchants expect.
- Track authorization rate, payment method mix, and cart abandonment by country. A single global conversion number hides where you're actually losing sales.
Localized presentation isn't cosmetic. It's the difference between a buyer recognizing a familiar flow and bailing at the final step, something borne out in broader research on ecommerce localization and keyword targeting by market as well.
Why Integration Matters More Than Any Single Feature
Most merchants don't lose money to bad payment methods. They lose it to reconciliation chaos, mismatched currency settings between checkout and funnel, and no clean record of which upsell or offer drove which international sale. An integrated setup, where payments and funnel logic share one dashboard, removes a layer of operational friction that separate tools can't. Multicurrency settings apply consistently across every offer instead of being configured tool by tool, and AI-assisted funnel optimization can adjust based on which markets and price points actually convert. That single-reconciliation view matters more once you're selling across ten currencies than any one payment feature does on its own.
What Tax and Regulatory Rules Apply to Foreign Payments?
Tax treatment of international payments depends entirely on where your business is registered and where your customer is located, and there's no single global rule to memorize. Many jurisdictions require you to register for a value-added or goods-and-services tax once you cross a sales threshold in that country, even without a physical presence there. The European Union, for instance, requires non-EU sellers of digital services to register under its One-Stop Shop scheme once they sell to EU consumers, regardless of sales volume in many cases.
Withholding tax is a separate issue: some countries require a portion of payments to non-resident businesses to be withheld at source, particularly for services rather than goods. Whether that applies to you depends on tax treaties between your country and your customer's, so a blanket assumption either way is risky.
Reporting requirements also vary by entity type. A sole proprietor accepting foreign payments faces different disclosure rules than an incorporated company, and some jurisdictions require reporting of foreign-currency holdings above certain balances.
None of this is something to guess your way through. Talk to an accountant familiar with cross-border digital sales before you scale into a new market, not after a tax authority sends a letter. The cost of getting this wrong (penalties, back taxes, blocked accounts) dwarfs the cost of an hour of professional advice. Keep records of where each customer is billed from, since that single data point determines most of your tax obligations across markets.

Cutting Chargebacks on International Orders
Cross-border transactions carry higher dispute rates than domestic ones, partly because unfamiliar billing descriptors and currency conversions confuse buyers who don't recognize a charge on their statement. The fix starts with your billing descriptor: make sure it clearly shows your business name, not a generic processor ID that means nothing to the cardholder.
Clear, itemized receipts sent immediately after purchase cut down on the "I didn't recognize this charge" dispute category significantly. Buyers in unfamiliar time zones from your support team also file more disputes simply because they can't reach anyone to resolve confusion before escalating to their bank.
Address risk before it becomes a chargeback:
- Use velocity checks and device fingerprinting to catch suspicious order patterns before they process, not after.
- Respond to disputes with compelling evidence (delivery confirmation, IP address, prior purchase history) within your processor's window. Missing that window is an automatic loss.
- Route higher-risk transactions (new customers, unusually large orders, mismatched billing and shipping countries) through additional verification like 3D Secure.
- Track your dispute rate by country. A single market driving a disproportionate share of chargebacks may need stricter checkout controls or removal from your active markets entirely.
Staying well under that line protects both your margins and your standing with processors.
Managing Refunds Across Borders
Refunding an international customer is rarely as simple as reversing a domestic charge. Currency fluctuations between the purchase date and the refund date mean the amount that lands back in a customer's account may not match what they paid, and that mismatch generates support tickets even when you did everything correctly.
Set clear expectations upfront. Your refund policy should state explicitly whether refunds are issued in the original charge currency or your settlement currency, and that minor differences due to exchange rate movement are normal and outside your control.
Processing times also vary widely by market and payment method. A card refund might post in three to five business days in one country and take two weeks in another, depending on the issuing bank. Bank transfer refunds across borders can take even longer, sometimes a week or more, because they route through the same slower settlement rails as the original payment.
A few operational habits reduce friction here:
- State your refund timeline in local terms ("5 to 10 business days" reads clearer than a fixed date that ignores weekends and holidays abroad).
- Automate refund confirmation emails so customers aren't left wondering whether a request went through.
- Flag high-refund-rate markets or products for review. Sometimes a pattern points to a product-market mismatch rather than a payments problem.
Cancellations for subscriptions carry their own wrinkle: prorated refunds calculated in one currency can look inconsistent to a customer paying in another, so document your proration method clearly in your terms.
Supporting International Buyers Across Time Zones and Languages
A buyer in Manila who hits a payment error at 2 a.m. their time and gets no response for eight hours is a buyer who charges back instead of waiting. Time zone coverage matters as much as language for reducing failed-payment friction.
You don't need 24/7 live staff to fix this. A well-written help center covering common payment issues (declined cards, currency confusion, refund timing) in your top three or four customer languages resolves a large share of tickets before anyone has to wait for a reply. Chatbots and async email support, staffed across overlapping shifts rather than a single time zone, close most of the remaining gap.
Language matters most at the exact moment of a payment failure, when customers are least patient and most likely to assume they've been scammed rather than that their card was simply declined. A translated, specific error message ("Your bank declined this transaction, try a different card or contact your bank") prevents far more abandoned carts and disputes than a generic English error page ever will.
Prioritize support coverage the same way you prioritize payment methods: by where your revenue actually comes from, not by guessing which markets might matter someday.
Data Privacy and PCI DSS for Cross-Border Transactions
Handling card data from international customers means navigating overlapping privacy regimes, and PCI DSS compliance is the baseline, not the whole picture. PCI DSS governs how you store, process, and transmit cardholder data regardless of where your customer lives, and a hosted checkout or tokenized payment flow shifts most of that scope onto your provider rather than your own servers.
Privacy law is where it gets more complex, because rules differ by where your customer is located, not where your business sits. The EU's General Data Protection Regulation applies to any business processing the personal data of EU residents, including payment and billing information, regardless of where the business itself is based. Other regions have their own frameworks with different consent, storage, and disclosure requirements, and a payment flow compliant in one jurisdiction can fall short in another.
The practical fix is choosing a payment provider that already carries current PCI DSS certification and gives you tokenized rather than raw card storage, which limits your own compliance burden considerably. Beyond that, keep your privacy policy specific about what payment data you collect, how long you retain it, and who processes it on your behalf, since vague boilerplate language is exactly what regulators flag first during a review.
A Founder's Take on What Actually Trips Merchants Up
The mistakes I see repeat: chasing one FX rate without checking realized spread, offering a single payment method and wondering why conversion lags, and treating KYC as an afterthought. Your first 90 days: research markets, enable local methods, set up multicurrency, test checkout weekly, and get your compliance documents in order before you need them.
— FanBasis
Sell Globally Without Juggling Five Different Tools
Most merchants patch together a payment gateway, a checkout builder, and a separate funnel tool, then spend hours each month reconciling numbers across all three. Some platforms attempt to put payments, checkout, and funnel logic in one dashboard, so a multicurrency sale, an upsell, and a subscription renewal all show up in the same place instead of three different exports you have to stitch together by hand.
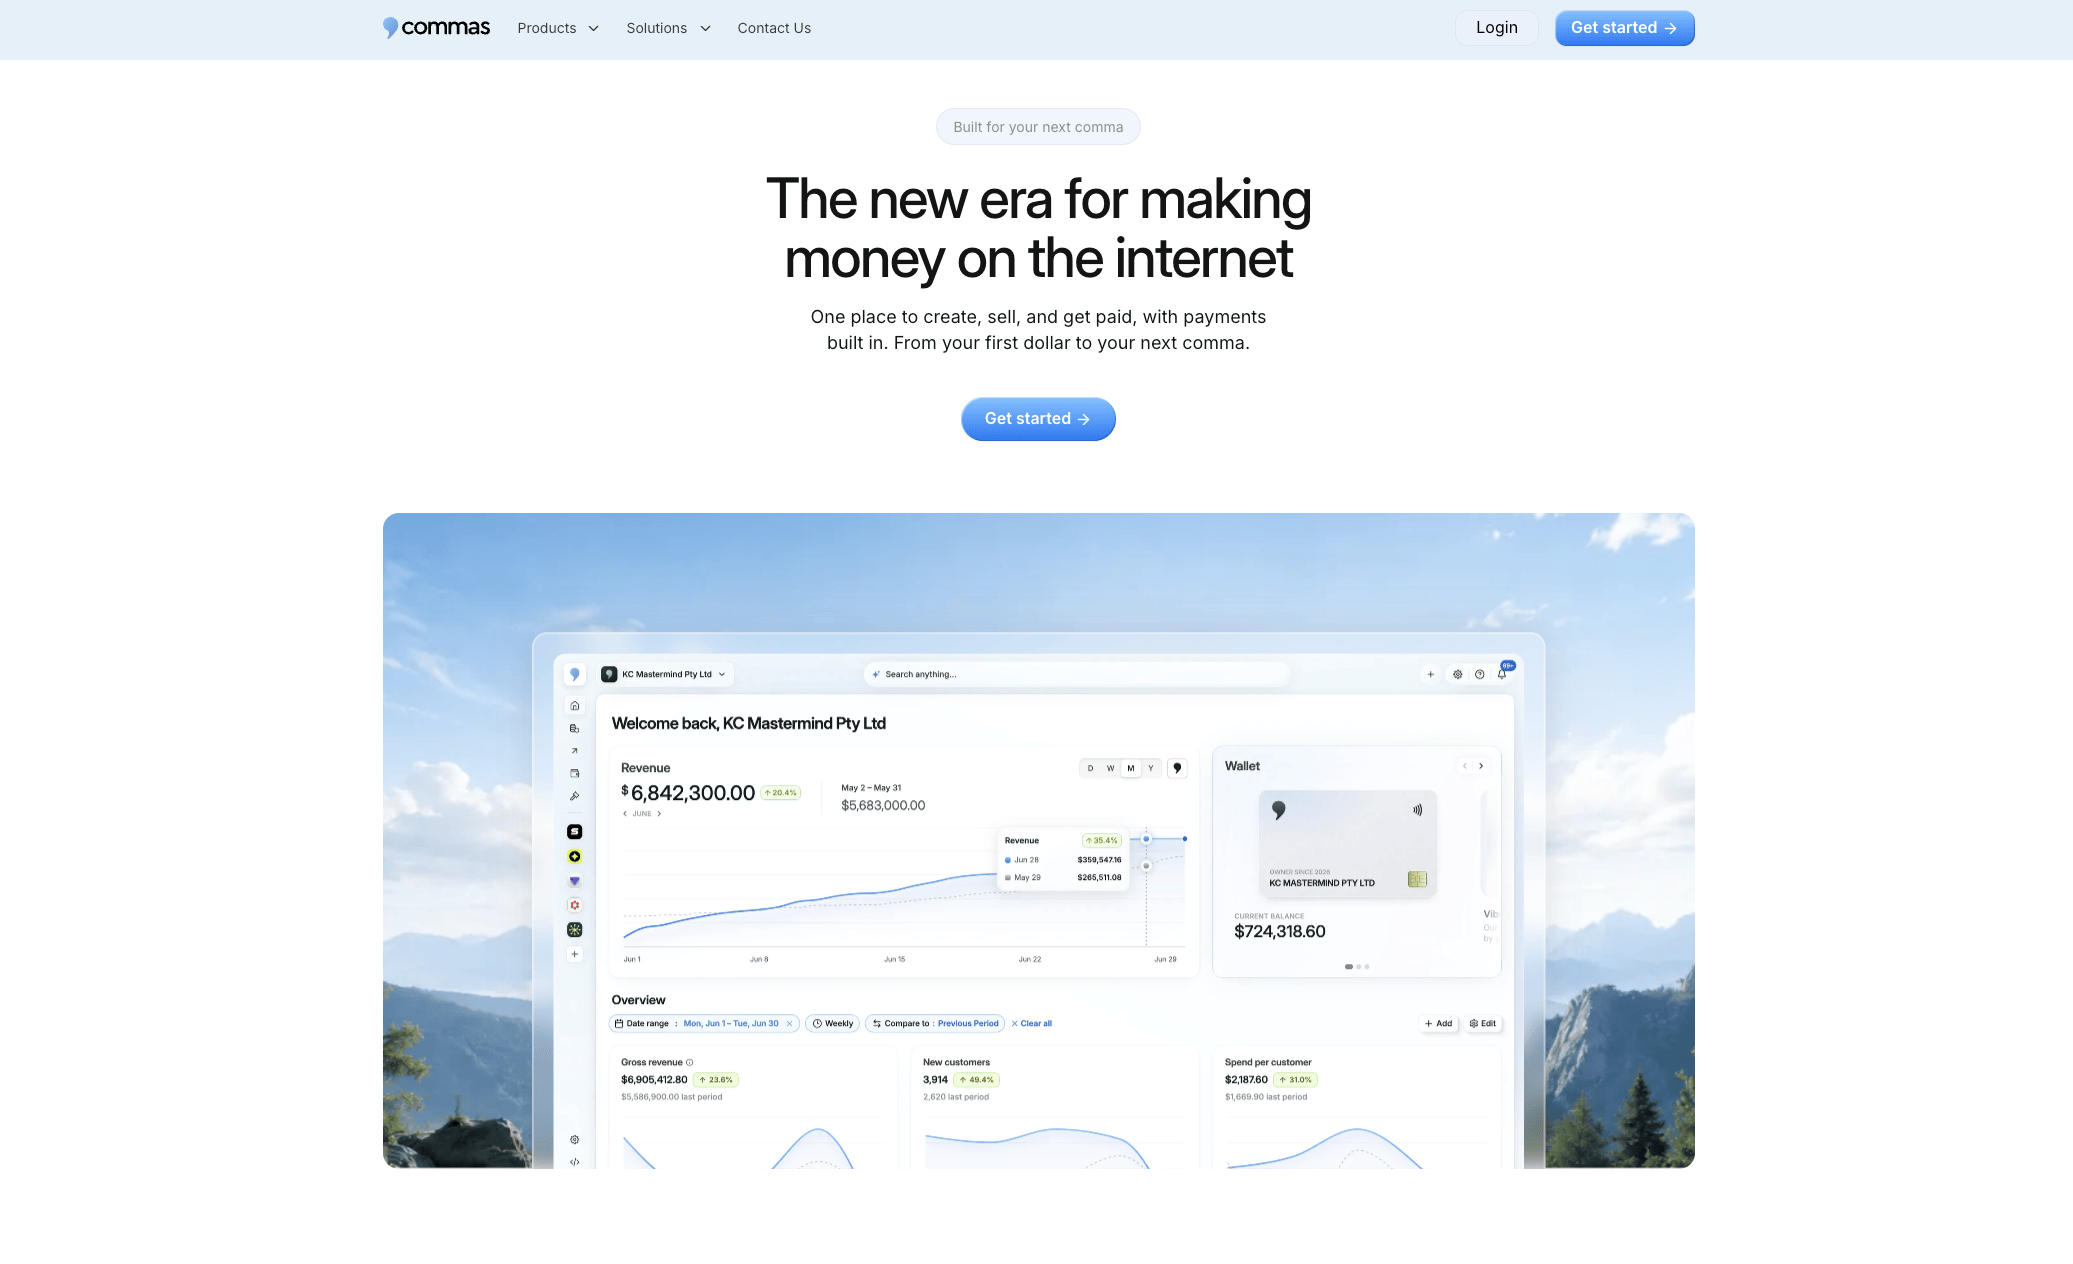
That matters most once you're selling to buyers in a dozen currencies with different payment habits. Commas Payments handles the acceptance side, including one-click checkout, BNPL, and subscriptions, while Vibe Funnels uses AI to adjust your sales flow based on what's actually converting in each market, rather than leaving you to guess. If you're a creator selling courses, coaching, or paid communities to an international audience, start by mapping your current setup to Commas Payments and see how much of your reconciliation work disappears in the first month.
Sources
A few primary sources back the compliance and cost figures throughout this guide:
- Cross-border payments - a catalyst for global integration and growth (BIS speech)
- Correspondent banking services and de-risking (FATF)
- EBA/ECB joint report on payment fraud and SCA (ECB)
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
FAQ
How Can I Accept Payments Internationally?
Choose a payment platform that supports multicurrency pricing, local payment methods, and built-in fraud and compliance tools, then localize your checkout for each target market. Platforms like Commas Payments combine acceptance, multicurrency settlement, and funnel-level checkout in one setup, which cuts down the reconciliation work of running separate tools.
Is Venmo or Zelle International?
Neither Venmo nor Zelle supports international transactions. Both are designed for domestic transfers between US bank accounts, so merchants selling to customers outside the United States need a dedicated cross-border payment gateway instead.
Does PayPal Accept International Payments?
Yes, PayPal Business accounts support holding balances in multiple currencies and offer conversion settings for merchants selling across borders. Fees and conversion rates vary by currency and country, so compare the realized spread against other providers before committing.
What Is the Easiest Way to Pay Someone Internationally?
For businesses, the easiest method is usually a payment platform or bank transfer that supports the recipient's local currency directly, avoiding a manual conversion step. For one-off personal transfers, licensed money-transfer services or bank wires remain the most widely accepted option, though cross-border transfers still average around 6.5% in cost for a $200 transaction.